
Launa Massola @ launao18913701 Member Since: 21 Sep 2026
 United States
About Me
The Role of Your Vehicle's Condition in Title Loan Approval
Lenders typically base the loan amount on a percentage of your vehicle's appraised resale value, factoring in age, mileage, and condition rather than the original purchase price. The exact percentage and maximum amount vary by lender and by state regulations.The vehicle itself goes through a valuation process, often based on mileage, condition, model year, and current market data, similar to how a trade-in value is calculated at a dealership. This valuation directly determines your loan amount, since lenders generally extend a percentage of the vehicle's appraised value rather than its full worth, leaving themselves a buffer in case they need to repossess and resell the car. A well-maintained vehicle with low mileage will typically qualify for a higher loan amount than an older vehicle with significant wear, even if both are paid off free and clear. It pays to weigh up Loans Inc. online title loans before you commit to a setup.
Borrowers dealing with genuinely urgent situations, sometimes searching specifically for emergency title loans, should build in a small buffer rather than assuming funds will land within hours. A realistic expectation is same business day to two business days for most approved applications, with funds typically deposited directly into a bank account once the lender finalizes the title transfer or lien placement. Anyone comparing offers should ask the matched lender directly about expected timing rather than relying on general marketing language, since actual funding speed is set by that lender's internal process, not by the matching service.
It depends on the lender. Many title lenders skip a hard credit inquiry entirely since approval is based on vehicle equity rather than credit history, but some do a soft pull that won't affect your score. Confirm this directly with the matched lender before submitting your application.
How Fast Is Funding, Really? Same-day title loans and emergency title loans are advertised widely because speed is the primary reason people choose this borrowing method over a traditional bank loan. In practice, funding speed depends on how quickly you can provide documentation, how fast the lender can verify the vehicle title and appraisal, and whether your state requires any additional waiting periods or notarization. Some borrowers do receive funds within hours of approval, particularly when applying during business hours and providing complete documentation upfront, but same-day funding is never guaranteed and should be treated as a possibility rather than a promise.
Once a potential match is identified, the applicant is generally directed to the lender's own platform to complete the formal application, which is where the lender collects the documentation needed to make an actual credit decision. This is also the point where a borrower first sees lender-specific terms, since every participating lender sets its own rates, fees, and repayment structure. It's worth noting that being matched with a lender is not the same as being approved - approval, loan amount, and pricing are decisions made solely by that lender after reviewing the application in full.
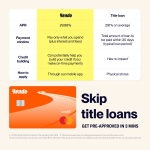
What Makes Auto Title Loans Different From Traditional Credit Products? Traditional loans, whether a personal loan or a credit card, are built around your credit history. Lenders pull your credit report, evaluate your score, and use that data to decide whether to approve you and at what interest rate. Auto title loans flip that model on its head: the loan is secured by the value of your vehicle rather than by your creditworthiness. This is why vehicle title loans are frequently marketed toward people with limited or damaged credit, since the car itself acts as collateral that reduces the lender's risk regardless of your credit score.
Fast Approval Versus Full Disclosure: Which Should You Prioritize? Fast title loans with quick approval are appealing precisely because they solve time-sensitive problems, but speed and thoroughness aren't always aligned, and it helps to know which one to prioritize at each stage. During the application itself, speed matters, since a faster online submission gets you in front of lenders sooner. Once you've received an offer, however, thoroughness should take over, because this is when you need written disclosures spelling out the annual percentage rate, total repayment amount, due dates, and any fees for late or missed payments. A lender who pressures you to sign before you've had time to read these disclosures is prioritizing their own speed over your understanding, and that's a signal worth heeding rather than dismissing. Reasonable lenders expect borrowers to take a few extra minutes to review terms, and a legitimate offer for emergency title loans will still be there after you've read the fine print once.
Consider a simplified example: suppose a borrower's vehicle is appraised at approximately $10,000 based on its condition and market comparables. A lender offering loans up to 40% of appraised value might extend an offer around $4,000, while a more conservative lender working at 25% might offer closer to $2,500 for the identical vehicle. This is precisely why comparing multiple lenders matters - the same car can generate meaningfully different loan offers depending on each lender's internal valuation formula and risk appetite. When this becomes a priority, Loans Inc. online title loans can make a real difference to your results.
Rating

The Best place to find a job and Make a difference with your Resume – We are Providing The most Suitable Companies for you.